


To make matters worse, sub-5% mortgage deals have almost entirely vanished from the market.
For the first time in roughly three years, borrowers interested in a five-year fixed mortgage are currently looking at paying 6% on average as lenders have continued to raise rates in response to persistent economic uncertainty.
This is according to latest analysis by Moneyfactscompare.co.uk, which also found the typical two-year fixed mortgage rate is quickly closing in on 6% after rising from 5.96% on Friday (2 October) to 5.98% this morning (Monday 5 October) - its highest point since mid-December 2023.
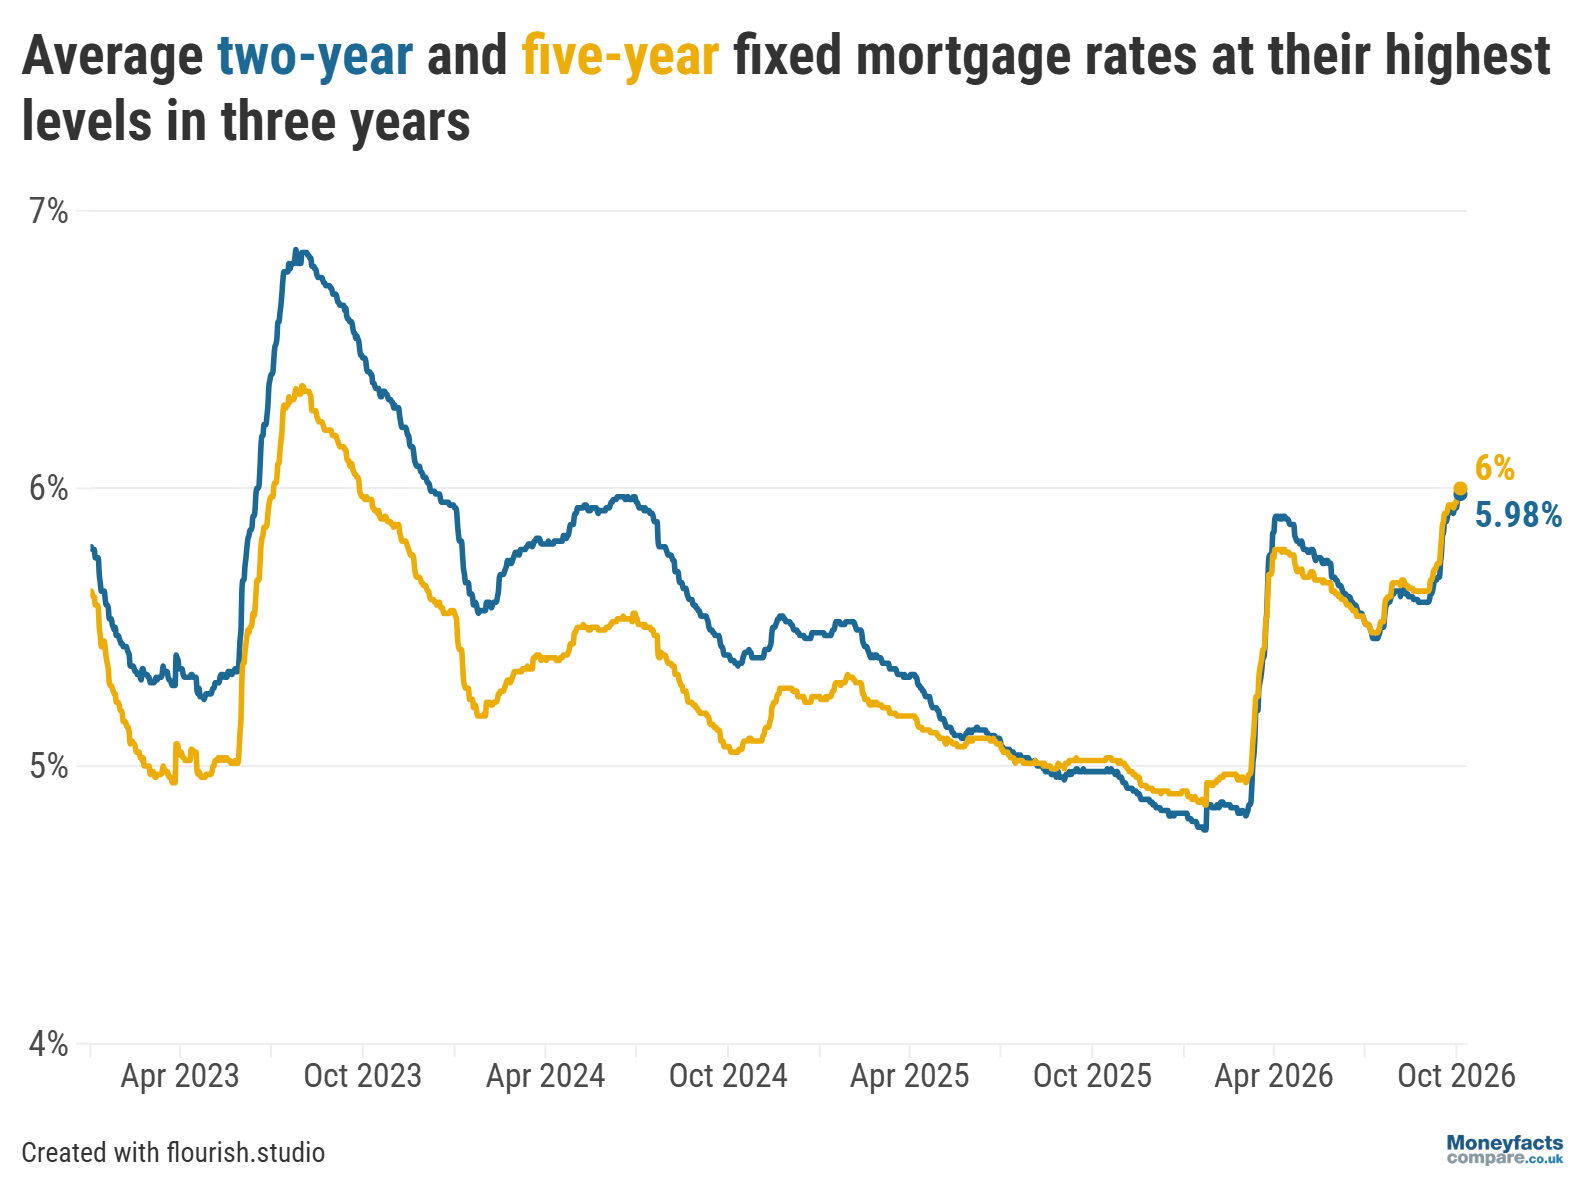
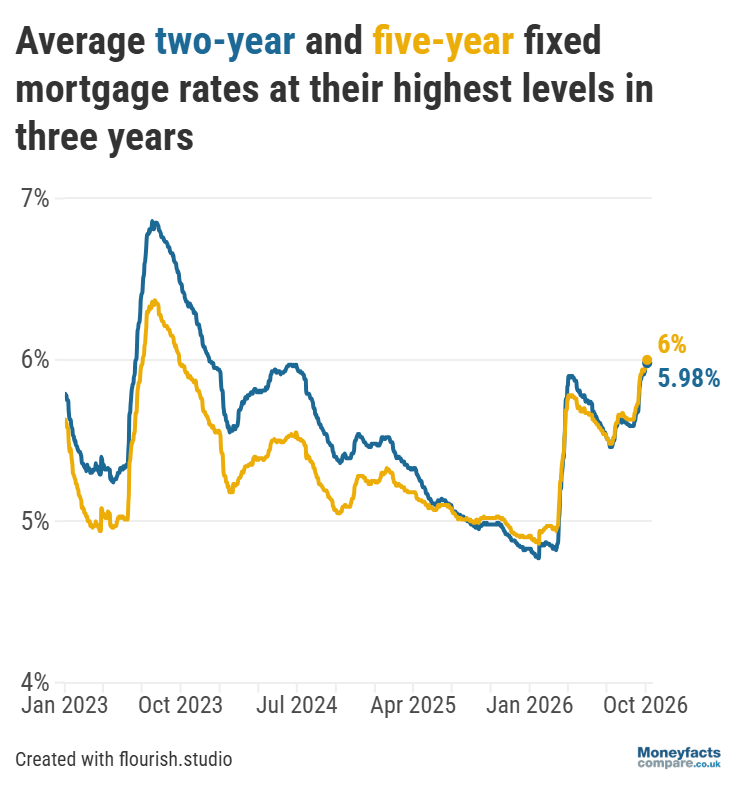
Latest UK Mortgage Trends: Average two- and five-year fixed mortgage rates between 2023 and 2026.
Some of the UK’s biggest high street lenders made multiple rounds of rate increases last month, including Barclays Mortgage (which hiked selected fixed rates on four occasions), as well as HSBC, Lloyds Bank, Nationwide BS, Santander and TSB (which each raised selected prices three times).
“The past few weeks have seen pricing margins among major lenders come under immediate pressure from renewed swap rate volatility,” Rachel Springall, Finance Expert at Moneyfactscompare.co.uk, explained. Swap rates (one of the main factors underpinning fixed mortgage pricing) recently soared as conflict in the Middle East continued to put pressure on oil supplies and fuel inflation fears, while a global bond sell-off pushed UK 10-year gilt yields to an 18-year high.
“Lenders look at their margins very carefully, so it would be unwise for them to price deals too low when swap rates and wholesale funding costs are elevated,” said Springall, as she explained what’s behind the recent trend.

While borrowers can still secure a below-average rate, fixed deals charging less than 5% have almost entirely vanished from the mortgage market. Nearly 1,500 fixed products were priced below 5% at the beginning of September, according to analysis by Moneyfactscompare.co.uk, however, this number plunged to just nine deals today*.
“This shows just how quickly the mortgage market has shifted for borrowers searching for the lowest rates,” said Springall.
By contrast, variable rate mortgages have so far proven more stable; currently 389 variable deals charge less than 5% (down slightly from 411 as the start of last month). “It may then be no surprise if borrowers are seriously considering a variable rate deal, such as a base rate tracker mortgage, particularly if it does not apply an early redemption penalty,” Springall added.
But, those opting for a variable rate deal should keep in mind there are expectations for the Bank of England to increase the UK’s central interest rate (known as the base rate) before the year ends, which could cause their monthly mortgage repayments to later rise.
Our charts are regularly updated throughout the day so you can easily find and compare the lowest mortgage rates.
But, remember that the deal charging the cheapest rate may not be the most suitable or cost-effective for your circumstances, so it’s important to consider all features of a mortgage carefully (including the lending area, any fees and incentives).
That’s why our weekly mortgage roundup not only summarises the mortgage deals charging the lowest rates, but it also offers some alternative options that earn spots on our Moneyfacts Best Buy chart based on their overall true cost.
Average fixed mortgage rates returning to three-year highs “will be disastrous news for borrowers,” Springall recognised. “Those coming to the end of a fixed deal would be wise to seek advice and compare deals carefully” to find the best option for their circumstances, “particularly as [they] could secure a new deal months before their existing mortgage ends”, she added.
Encouragingly, Oliver Dack, Spokesperson for Mortgage Advice Bureau, said he’s already seen greater proportions of remortgage borrowers reach out for advice over the past couple of months.
“While the outlook may seem bleak, it’s not all doom and gloom,” said Dack. “Lenders are still actively looking to extend loans, so it’s more a matter of affordability. And, although mortgage rates have been creeping higher, wage growth has outpaced house price growth, which may help offset some of the impact of higher borrowing costs on affordability,” he explained.
However, Dack also urged anyone who is struggling to meet their repayments or worried about interest rates to seek advice, as there could be ways to alleviate the pressure.
MAB is the preferred mortgage broker of Moneyfactscompare.co.uk
Get friendly, expert advice free of charge as a visitor of Moneyfactscompare.co.uk
Mortgage Advice Bureau have 1,600 UK advisers with 200 awards between them.
Speak to an award-winning mortgage broker today.
Call 0800 031 8553 or request a callback
Mortgage Advice Bureau offers fee free mortgage advice for Moneyfactscompare.co.uk visitors that call on 0800 031 8553. If you contact Mortgage Advice Bureau outside of these channels you may incur a fee of up to 1%. Lines are open Monday to Friday 8am to 8pm and Saturday 9am to 1pm excluding bank holidays. Calls may be recorded.
Your home may be repossessed if you do not keep up repayments on your mortgage.
*Excluding deals only available for lending in Northern Ireland.

All of our newsletters are available free by email to all Moneyfactscompare.co.uk users.
Send me Weekend Moneyfactscompare, Savers Friend, and Companies Friend.
Information is correct as of the date of publication (shown at the top of this article). Any products featured may be withdrawn by their provider or changed at any time. Links to third parties on this page are paid for by the third party. You can find out more about the individual products by visiting their site. Moneyfactscompare.co.uk will receive a small payment if you use their services after you click through to their site. All information is subject to change without notice. Please check all terms before making any decisions. This information is intended solely to provide guidance and is not financial advice. Moneyfacts will not be liable for any loss arising from your use or reliance on this information. If you are in any doubt, Moneyfacts recommends you obtain independent financial advice.

Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.
Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.
Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.
Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.
Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.
Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.

