


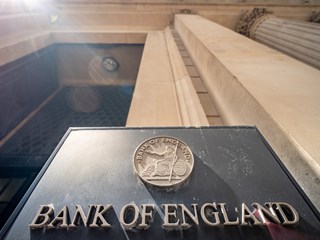
Many predict the central bank could raise rates in November.
The Bank of England’s Monetary Policy Committee (MPC) has voted to keep the base rate at 3.75% for a sixth consecutive time despite UK households and businesses facing growing pressure from inflation.
Only yesterday, it was revealed that the rate at which prices of goods and services are rising accelerated to 3.1% in the year to August – a five-month high and more than one percentage point above the central bank’s 2% target. This increase was largely due to fuel prices becoming more expensive as ongoing conflict in the Middle East continues to disrupt global supply chains.


Latest UK economic trends: Graph showing the Bank of England base rate and the rate of inflation between 2020 and 2026.
The base rate is the amount of interest the Bank of England charges commercial banks, building societies and other financial institutions to borrow money. In turn, it influences the amount of interest these organisations charge their own borrowers and pay savers.
As such, it can be used as a tool by the Bank of England to keep inflation in check. For example, during periods of high inflation, the central bank might increase the base rate to reduce demand (by making it more expensive to borrow money and more rewarding to save). By contrast, the UK's central bank could lower the base rate to stimulate economic growth (by making borrowing cheaper to encourage greater levels of spending).
Learn more about inflation and the Bank of England base rate.
Worryingly, in a worst-case scenario, the Bank of England currently projects that inflation could reach as high as 4.5% in the second quarter of next year as a direct result of substantially higher energy prices. Such concerns have fuelled expectations for the MPC to increase the base rate at its next scheduled meeting (on 5 November 2026) in a bid to keep rising costs in check.
But, even though the base rate has remained unchanged so far this year, there hasn’t been much respite for borrowers.
The past few weeks alone have seen waves of rate hikes from mortgage lenders as they react to inflation forecasts and volatility in the swap market, Rachel Springall, Finance Expert at Moneyfactscompare.co.uk, explained. She added that some lenders, including NatWest, Santander, HSBC and TSB, have even increased selected fixed mortgage rates for a second time this month.
As a result, the average rate charged by a two-year fixed mortgage deal rose from 5.63% at the beginning of August to 5.73% earlier this week (15 September 2026). Meanwhile, the average five-year fixed mortgage rate made an even bigger jump from 5.66% to 5.78% over the same timeframe.
“The mortgage pain shows no sign of easing for those borrowers who cannot yet lock into a new deal, particularly those with a five-year fix who are not due to refinance until 2027,” said Springall. “Back in February 2022, there were sub-2% fixed mortgages available, so moving off this rate will be a huge shock for borrowers,” she added.


Latest UK mortgage trends: Average two- and five-year fixed mortgage rates between 2020 and 2026 shown alongside the Bank of England base rate.
Our mortgage charts are regularly updated throughout the day so you can easily explore the lowest rates currently available.
But, keep in mind that the deal charging the cheapest rate may not be the most suitable or cost-effective for your circumstances, which is why it's important to consider all features of a mortgage carefully (including the lending area, any fees and incentives).
For this reason, our weekly mortgage roundup not only provides a summary of the cheapest-priced mortgage deals, but also offers some alternative options that earn spots on our Moneyfacts Best Buy chart based on their overall true cost.
The upcoming Autumn Budget might be among reasons the MPC held off making any changes to the base rate this time around, as any new measures unveiled have the potential to alter economic forecasts.
However, anyone delaying their mortgage search while they wait to see if the Government announces additional support for buyers is being urged to “drown out the political noise and concentrate on their personal situation” by Oliver Dack, Spokesperson at Mortgage Advice Bureau.
“Putting off finding a mortgage will likely only add to borrowers’ frustrations in the long run,” Dack warned. “Even if the Budget contains changes that could improve affordability, it’s unlikely these would take immediate effect. In the meantime, mortgage rates could climb even higher and existing borrowers risk reverting to a lender’s expensive Standard Variable Rate,” he explained.
“We’re encouraging those coming off a fixed rate to book a new deal sooner rather than later,” Dack continued. “Rest assured that we regularly monitor the market and will look to move our clients onto a cheaper deal if one becomes available before their start date,” he added.
That being said, not every lender lets customers lock in a new mortgage up to six months ahead of their current deal ending. “It is vital that lenders and brokers help customers understand the implications of ending their deal early, such as the early repayment charges,” said Springall.
The Autumn Budget is an opportunity for the Chancellor of the Exchequer to update Parliament on the latest economic forecasts, as well as the Government's plans for tax and spending.
In theory, the Budget could include new tax measures, spending commitments, policy reforms, investment proposals, business incentives or changes to household support. Find out what we know so far ahead of Autumn Budget 2026.
Meanwhile, with the Bank of England estimating that around £300 billion is sitting in accounts earning no interest, UK savers could be missing out on a combined total of £12 billion a year in interest if this money instead earned a rate of 4%, according to analysis by Moneyfactscompare.co.uk.
“Amid a cost of living crisis, every pound counts,” said Springall. “Saving little and often is the key to building a healthy nest egg, but an even bigger difference can be made by putting spare payday cash into an inflation-busting savings account,” she continued.
But, while Springall explained that easy access accounts are a “firm favourite” among savers due to their flexibility, she also said that “not every saver will make time to open one” or will hold one “with their main bank for convenience”. She warned that this oversight comes at a cost, as some of the most flexible accounts from big banks pay just 1.16% on average*.
By contrast, over 190 easy access accounts could better the rate of inflation at the time latest figures were released yesterday, with some of the most competitive options currently offering 4.00% or more.


Latest UK savings trends: Average easy access, one and two-year fixed savings rates between 2020 and 2026 shown alongside the Bank of England base rate.
Our savings and ISA charts are updated every day between 9am and 5pm so you can easily find and compare the best rates currently available.
Also check out our weekly savings and ISA roundups for more information on some of the most competitive accounts, or subscribe to our Savers Friend newsletter for free to receive weekly updates from across the savings market.
*Big bank easy access selection: Barclays Bank, Everyday Saver, 1.00%. HSBC, Flexible Saver, 1.04%. Lloyds Bank, Easy Saver, 0.75%. NatWest, Flexible Saver, 1.00%. Santander Easy Access Saver, 2.00%.

All of our newsletters are available free by email to all Moneyfactscompare.co.uk users.
Send me Weekend Moneyfactscompare, Savers Friend, and Companies Friend.
Information is correct as of the date of publication (shown at the top of this article). Any products featured may be withdrawn by their provider or changed at any time. Links to third parties on this page are paid for by the third party. You can find out more about the individual products by visiting their site. Moneyfactscompare.co.uk will receive a small payment if you use their services after you click through to their site. All information is subject to change without notice. Please check all terms before making any decisions. This information is intended solely to provide guidance and is not financial advice. Moneyfacts will not be liable for any loss arising from your use or reliance on this information. If you are in any doubt, Moneyfacts recommends you obtain independent financial advice.

Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.
Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.
Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.
Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.
Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.
Moneyfactscompare.co.uk will never contact you by phone to sell you any financial product. Any calls like this are not from Moneyfacts. Emails sent by Moneyfactscompare.co.uk will always be from news@moneyfacts-news.co.uk. Be ScamSmart.

